The month ended. The sales were good, the P&L is in profit and there is nothing seriously incorrect.
You then check the bank account of the restaurant.
You didn’t get the number you would have expected.
Restaurant owners may be frustrated by this as they believe cash flow and profits ought to be identical. However, they aren’t. The P&L is a metric of financial performance. In contrast, the bank account is a record of how much money is moved in and out.
Knowing the differences can help owners change their perception of restaurant financials.
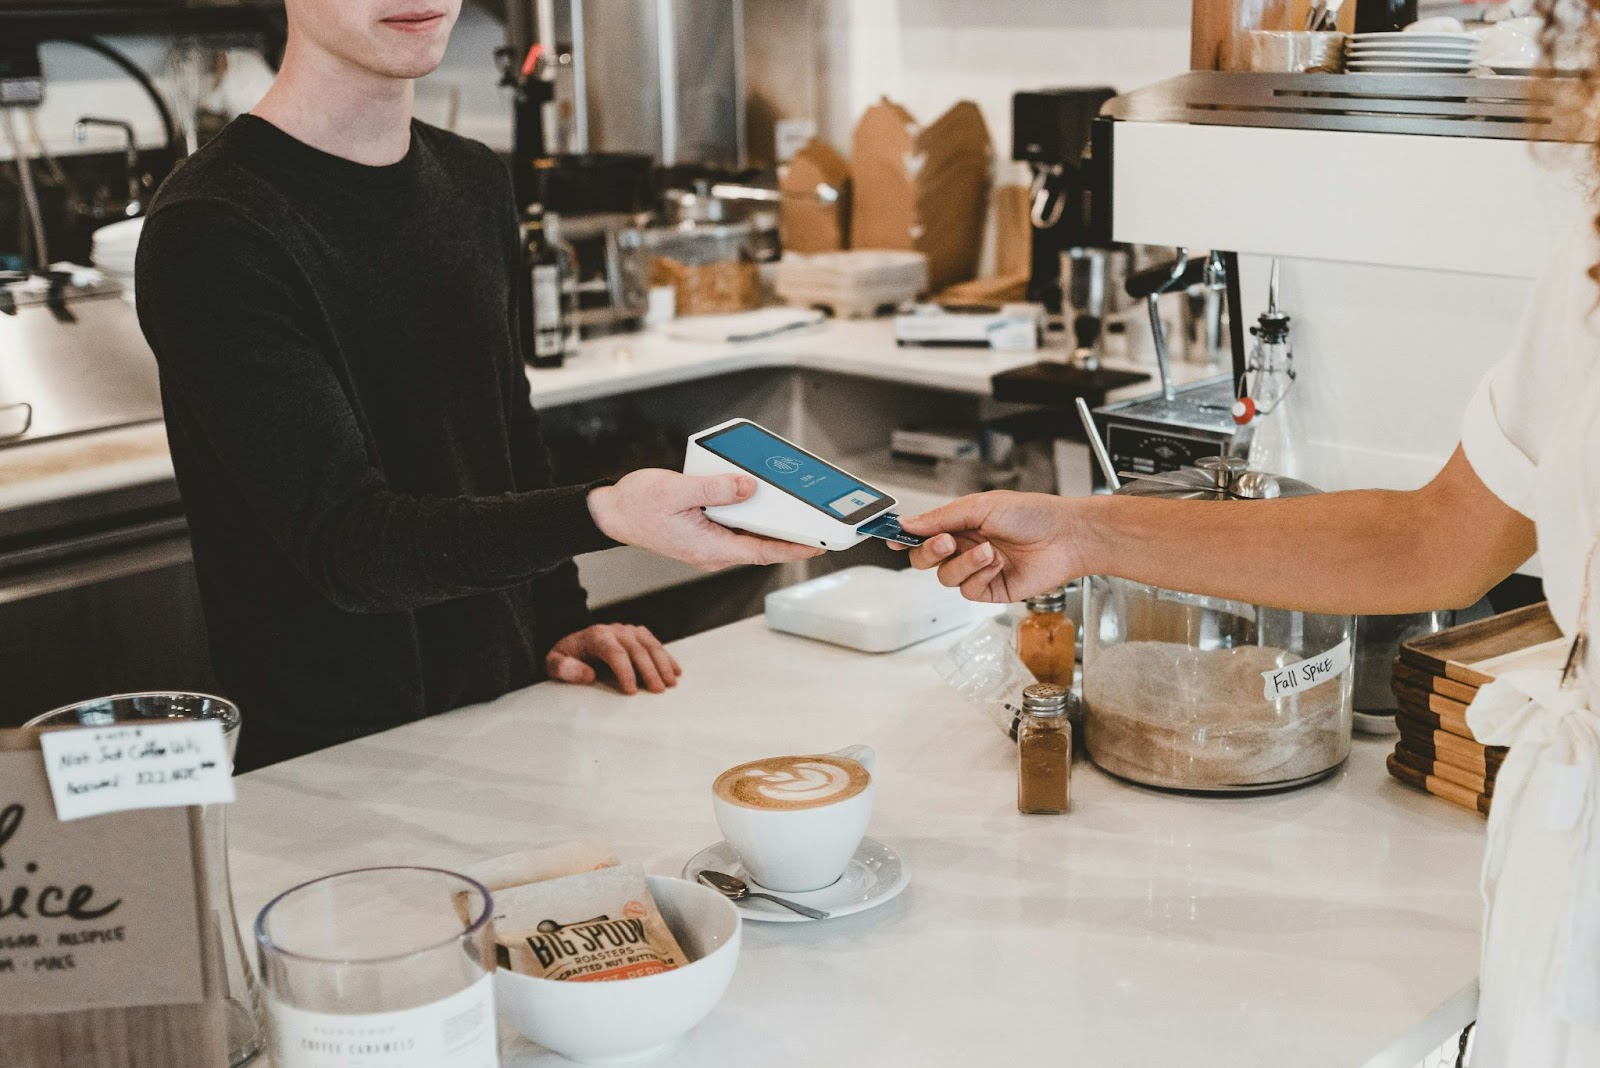
Look at what happens during a normal week. Food is paid for by customers. Employees have to be paid. You will receive invoices with the delivery of food and drinks. Rent is coming. Credit card payments are timed. Sales tax is an obligation.
Already, the next week’s purchases have started.
If you are only looking at the amount of revenue or the final profit, then you will be missing a lot of the activity.
Prime Cost could be the key to the answer
If restaurant profitability begins to decline, the costs of food, beverages and labor costs must be taken into consideration.
Prime cost is composed from both materials and labor. Bookkeeping Chef’s guidelines place prices for the prime cost at around 60% to 65 percent for most restaurants and stresses weekly monitoring rather than staying until the end of of the month.
It is more important to be able to detect the changes before they occur rather than obsessing over certain percentages.
If the restaurant typically performs near its target but this week, it’s at a higher percentage. Perhaps the overtime rate was increased. Maybe beverage costs were stable however food costs increased. The chef may look over menus and portions, waste as well as vendor invoices and purchasing if the food percentage is higher.
The percentage is the most important. The restaurant’s activity is the answer.
A weekly report can make this conversation possible and everyone is still able to remember what happened.
After two or three weeks, it becomes much more difficult to reconstruct details.
The Vendor’s bills arrive
Restaurants may buy ingredients in one week, and then pay for them next week. Because of this, it is the case that understanding profits alone can not resolve all cash-related issues.
Vendor invoices must be tracked, accepted and paid. In a busy operation with numerous suppliers, doing that manually can turn into an administrative burden.
Automation of accounts payable streamlines the process by reducing tedious tasks such as managing the payment and bill details. Systems for bookkeeping that are linked can give owners a better image of their obligations even if they’ve not yet been paid.
It’s helpful because, when considered as a whole the bank balance of a restaurant could appear to be more healthy than its actual short-term financial situation.
There could be $80,000 in the account right now. This number could mean something different in the event that payroll, rent and vendors as well as other obligations consume a significant portion of it over the next few days.
That leads naturally to cash flow forecasting.
What happens to our cash once we’ve received the money that we expect and have met our obligations?
It is essential to be aware of the difference when deciding if this week is the best time to replace equipment, buy more items, or conserve the cash flow.
You might not have been eligible for all the money you believed.
Sales tax illustrates the point especially well.
Restaurants take money from their customers, which they must follow according to their tax obligations. If these cash-flows are combined with operating cash, it could provide a false perception of the cash available for spending.
Consistent records support sales tax compliance while also giving management a more realistic picture of the financials of the restaurant.
Accounting for restaurant operations is more effective when the financial obligations of each restaurant do not have to be treated separately.
Prime cost affects margin. COGS and future payments are impacted by purchases from vendors. Payroll has an impact on the percentage of labor and cash. Taxes on sales affect cash availability. P&Ls are used for recording the financial performance. Forecasting is also beneficial for managers.
The pieces are connected.
Bookkeeping Chef assists in bringing these pieces together with restaurant-focused reports as well as system integrations. Specialized outsourced bookkeeping services can be a good alternative for businesses that don’t have the time to manually reconcile financial data. They can take care of much of the accounting work while removing the proprietor from the financial conversation.
The last section is very important.
It’s not the aim of restaurant owners to not check their books just because someone else does. It is important that owners have access to information so that they know what’s going on.
So when the P&L states that the restaurant has made money, but the bank account feels surprisingly unbalanced, don’t think that some of the figures must be incorrect.
Ask them about what transpired between them.
That question can teach you more about your restaurant than any number be on its own.